Incentive Schemes in Capital Goods Sales – Between Motivation and Misaligned Incentives
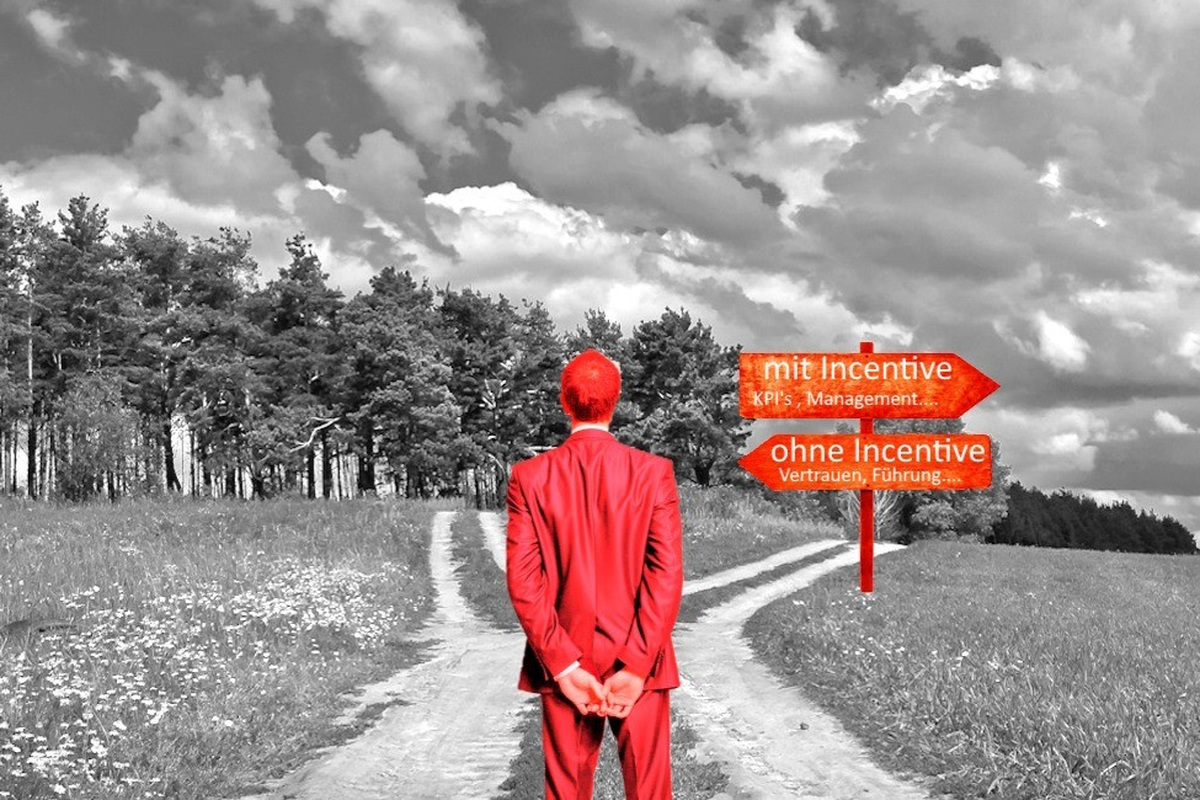
Sales is a key driver of growth and profitability – particularly in the capital goods industry. This raises a recurring question: how do you motivate salespeople to perform at their best? How do you encourage them to go the proverbial extra mile without reinforcing unwanted side effects such as short-term thinking or internal competition?
One of the most widely used tools for directing sales performance is the incentive scheme – and it remains a perennial topic of debate.
But what do variable pay schemes actually achieve? And where do their limitations lie?
1. The basic idea: performance should be rewarded
Incentive schemes follow a seemingly simple principle: those who sell more should earn more.
This performance incentive is intended to motivate people, strengthen their focus on objectives and ultimately improve business results. In theory, this sounds plausible – and fair.
The approach seems particularly attractive in technically demanding capital goods sales, where win rates, project cycles and margins vary considerably.
But does it work in practice?
2. The benefits of a well-designed incentive scheme
a) Increasing motivation and commitment
A transparent bonus scheme can provide additional motivation for ambitious employees. Financial incentives may encourage performance-driven individuals in particular to improve on their previous results.
b) Focusing on business objectives
Well-designed incentive schemes can translate strategic objectives into specific performance expectations. These might include increasing contribution margins, promoting particular product lines, acquiring new customers, developing existing customer relationships or entering new markets.
c) Making performance measurable and manageable
Metrics such as revenue, margin or customer visit frequency provide a seemingly objective basis for assessing performance. They make it easier for managers to direct sales activities – at least at first glance.
d) Encouraging constructive competition
When designed appropriately, performance incentives can encourage constructive competition within the sales team. However, this requires team contributions to receive due recognition and employees to regard the rules as transparent and fair.
3. The challenges lie in the detail
In practice, however, incentive schemes can also encourage undesirable behaviour and, in the worst case, become counterproductive – particularly when they do not reflect how the business actually operates or its corporate culture.
a) Short-term thinking
An excessive focus on short-term metrics can lead salespeople to prioritise quick wins, even when these are unprofitable in the long term or strategically disadvantageous.
Lasting customer relationships and long-term growth can suffer as a result.
b) Undervaluing team contributions
Particularly in project-based business, sales success is often the result of a collective effort.
If only the person who ultimately closes the deal is rewarded, important contributions from others – such as engineering, development, project management or pre-sales – go unrecognised.
This can undermine the motivation of those involved and weaken collaboration across departments.
c) Demotivation when targets are missed
Missing a target is not always the result of poor performance.
Supply constraints, quality problems, changes in the market or customers postponing investment decisions can significantly affect sales results.
When variable pay accounts for a very large share of total remuneration, these external factors can quickly lead to frustration and a sense of unfairness.
d) Excessive complexity and a lack of transparency
Points systems, bonus curves, target adjustments and special provisions: incentive schemes tend to become increasingly complex over time.
What was originally intended to provide a transparent and clear assessment of performance becomes increasingly difficult to understand.
As a result, employees lose track of how the scheme works – and potentially lose confidence in its fairness.
e) Optimising KPIs instead of improving actual performance
Problems become particularly acute when the focus shifts from creating value for the business to finding clever ways of meeting individual metrics.
Examples from practice include:
- Orders are deliberately deferred to the next financial year to avoid bonus caps.
- The definition of a new customer is interpreted creatively.
- Customer visits are counted multiple times by visiting different departments within the same company.
- Target industry definitions are interpreted flexibly to meet agreed metrics.
The obvious response – trying to prevent such behaviour through ever more precise KPI definitions – often creates even greater complexity without necessarily improving sales performance.
4. The particular characteristics of capital goods sales
Capital goods sales differs in several respects from conventional product or consumer goods sales.
These characteristics make it more difficult to design fair and effective incentive schemes:
- Long sales cycles: The period between the initial development of a project opportunity and receipt of an order is often six to 24 months. Assessing performance within a single financial year therefore frequently provides an incomplete picture.
- Extensive customisation: Projects often differ considerably in scope, technical requirements, margins and decision-making processes. Direct comparisons based on a small number of metrics therefore have limited value.
- Team-based delivery: Sales is often just one of several functions involved in winning business. Engineering, development, project management and senior management also make important contributions to success.
- External dependencies: Regulatory requirements, customers’ investment budgets and economic conditions can have a significant impact on sales results.
- Different project durations: Whether order intake or revenue is the more appropriate target measure depends largely on the business model and the timing of project delivery.
A simple bonus scheme based exclusively on revenue often fails to reflect these interdependencies.
5. The case for a tailored approach
No single incentive scheme is equally suitable for every company.
The crucial question is:
Does the pay scheme fit the strategy, corporate culture, business model and people involved?
Where variable pay is used, it should form part of a broader leadership culture.
Important design principles include:
- Combine individual and shared objectives: Team contributions should be recognised to avoid excessive internal competition and the pursuit of individual interests.
- Include qualitative criteria: Customer satisfaction, proposal quality and the long-term development of customer relationships can provide important complements to purely quantitative metrics.
- Involve managers actively: Agreeing targets and assessing performance require a nuanced understanding of the actual business conditions.
- Limit the proportion of variable pay: A balanced relationship between fixed salary and performance-related pay can combine financial security with motivation.
- Establish simple and transparent rules: Employees must be able to understand which contributions are assessed and how these determine their pay.
- Review and adapt regularly: Strategic changes, new market conditions or evolving business models may require adjustments.
In some companies, it may even be more appropriate to dispense with individual bonuses altogether and instead use collective profit sharing or non-financial sources of motivation.
Conclusion: sales success requires more than financial incentives
An incentive scheme is not an end in itself. It can encourage commitment and support strategic objectives – but it can also encourage undesirable developments if it does not fit the realities of the business.
Capital goods sales in particular requires an understanding of sales success from a whole-system perspective. Successful customer projects rarely result from one person’s efforts alone. They emerge from the interaction of different functions and areas of expertise.
Supporting lasting sales success therefore requires more than financial incentives.
It requires a corporate culture in which performance is enabled, recognised and meaningful – and managers who provide real leadership instead of merely administering metrics.